Abstract
This paper asks what the number 70 in RSI belongs to — the answer is that it belongs not to the market but to the bar size one chose. It claims neither a new mathematical theorem nor a new law.
First, holding the thresholds at 30/70 and changing only the bar size, the share of time RSI sits outside them runs from 8.5015% on five-minute bars to 16.2095% on four-hour bars. The ratio across bar sizes has a median of 1.6130 (Section 3).
Second, and this is the core of the paper, on series built from independent normal increments the same ratio is flat, between 1.0921 and 1.0980. The dependence on bar size therefore does not come from the definition of RSI; it comes from the market (Section 6).
Third, moving the thresholds from 60 to 80 changes the share selected by a factor of 19.0345 to 36.6540. Choosing a threshold is choosing how rare an event to pick up (Section 4).
Fourth, measuring the directional information, the daily-clustered t reaches 2 in absolute value in 10 of the 16 cells. By chance about 0.7 would be expected, so stopping here reads as "it works" (Section 5).
Fifth, but removing overlapping windows drops the same figure to 2 of 16. The count falls to 0.0244 of itself and the sign reverses in 4 of the 16 cells. The horizon was twenty-four hours while entries were taken every five minutes, so adjacent observations shared 287 of their 288 minutes (Section 7).
Sixth, and the measured directional information falls inside the range of the 20 synthetic realisations in all four series (Section 7).
Scope of this paper (scope note): No new mathematical theorem and no new law is claimed — the definition of RSI, Wilder's smoothing and random walks are all known. No particular product or proponent is discussed — no real course, author, or vendor is the subject here, and none is named. What is treated is the public indicator itself. Trading is not discussed — what is measured is directional information, not trading performance including commissions, fills and money management. The scope is intraday and a small number of instruments — four series, six years, four bar sizes. Nothing is said about all markets or all time scales. In particular, this paper does not contradict results documented at longer holding periods, such as monthly time-series momentum. Only the mean-reverting reading is measured — the trend-following reading (buy at 70, sell at 30) is the same signal with its sign flipped, so its directional information is the same number with its sign flipped. Divergence is not treated — reading a disagreement between price and RSI is not a question about thresholds and lies outside this paper. No forecast is claimed. Relation to earlier papers: Paper 264 showed that a threshold belongs to its lattice — this paper measures that in a market indicator. Paper 422 showed that removing the condition named as the core of a rule does not move the result. F003 of this series showed that the multiplier of a Bollinger band moves only how often price leaves it — this paper measures the same shape on another number, the overbought threshold. What is added here is declaring the bar size as the separator in advance and measuring it at four values, writing in advance the prediction that a series of independent increments should not depend on bar size and placing it beside the measurement, and placing the form with overlapping windows removed in the same table.
1. Notation and the question
RSI is built as follows. Differences of closes are split into rises and falls, each is passed through Wilder's smoothing (with coefficient the reciprocal of the period), and their ratio is mapped to a value between 0 and 100. A period of 14 is widely used.
The common reading is that 70 or above is overbought and 30 or below is oversold.
Observation 1.1: this number 70 has no meaning until the bar size is fixed. The 70 of a five-minute bar and the 70 of a four-hour bar are the same number but not the same event.
Observation 1.2: it does not follow, however, that they must differ. RSI is built from the ratio of rises to falls, so it does not depend on the size of the moves. On a series of independent increments, the distribution of RSI should not depend on bar size.
Question: as the bar size changes, what does the same 70 select? And what happens in a market?
Observation 1.3: two predictions follow.
Prediction A (the threshold belongs to the lattice) — the same 70 selects a different share at a different bar size.
Prediction B (the threshold points at a state) — the share is about the same regardless of bar size.
A random walk should give Prediction B. The question is therefore settled by how far the measurement departs from it.
2. Writing the quantity and the design in advance
Two quantities are measured.
One is the share of time RSI sits outside the thresholds. The other is directional information.
```
D = mean( sign of the signal × the price move over the next h bars ) in pips
```
The signal is −1 (sell) when RSI is 70 or above, +1 (buy) when 30 or below, and 0 between them. This is the mean-reverting reading. The trend-following reading is its sign flipped and is not measured.
Observation 2.1: the horizon is fixed at twenty-four hours of clock time. The number of bars therefore differs by bar size (288 on five-minute, 96 on fifteen-minute, 24 on one-hour, 6 on four-hour bars). Without this, four-hour bars would move more as a matter of course.
Design (declared before running and unchanged at run time)
| Item | Decision |
|---|---|
| Indicator | RSI, period 14, Wilder's smoothing |
| Bars | mid price, closing value of completed bars only (the last tick in the bar) |
| Instruments | USDJPY, EURUSD, GBPUSD, XAUUSD |
| Period | 2019–2024. Selection 2019–2021 / evaluation 2022–2024 |
| Horizon | twenty-four hours of clock time (the number of bars varies by bar size) |
| Separator | bar size: 5 min, 15 min, 1 hour, 4 hours |
| Thresholds | 40/60, 30/70, 20/80 (standard is 30/70) |
| Period n | 7, 14, 21 (standard is 14) |
| Cost | the median spread of the same bars is always reported alongside |
The bar counts are as follows.
| Instrument | 5 min | 15 min | 1 hour | 4 hours |
|---|---|---|---|---|
| USDJPY | 438,283 | 146,125 | 36,534 | 9,640 |
| EURUSD | 438,505 | 146,202 | 36,554 | 9,648 |
| GBPUSD | 438,199 | 146,127 | 36,535 | 9,644 |
| XAUUSD | 418,478 | 139,501 | 34,892 | 9,442 |
3. Changing the bar size — this is the separator
Calculation 3.1 The share the same 70 selects (evaluation period, thresholds fixed at 30/70)
| Instrument | 5 min | 15 min | 1 hour | 4 hours | Max ÷ min |
|---|---|---|---|---|---|
| USDJPY | 9.3756% | 10.8310% | 14.6152% | 16.2095% | 1.7289 |
| EURUSD | 8.6028% | 9.5140% | 11.8048% | 12.8785% | 1.4970 |
| GBPUSD | 8.7676% | 9.2814% | 11.4524% | 11.1457% | 1.3062 |
| XAUUSD | 8.5015% | 9.8677% | 12.6550% | 15.3115% | 1.8010 |
Observation 3.2: the ratio across bar sizes has a median of 1.6130 (minimum 1.3062, maximum 1.8010). The same 70 selects between 1.3 and 1.8 times as much time depending on the bar size.
Observation 3.3: the direction is consistent. In three of the four series the share grows with the bar size. Only GBPUSD has the four-hour figure slightly below the one-hour figure (11.1457% against 11.4524%).
Observation 3.4: at this point it is not yet known whether this is a property of the market or of the definition of RSI. The baseline of Section 6 separates them.
Calculation 3.5 The quantiles of RSI itself (evaluation period, USDJPY)
| Bar size | 5% | 25% | 50% | 75% | 95% |
|---|---|---|---|---|---|
| 5 min | 31.2984 | 43.1382 | 51.1103 | 58.9041 | 70.4023 |
| 15 min | 30.9084 | 43.4603 | 51.6618 | 59.5808 | 71.7251 |
| 1 hour | 29.8778 | 43.7160 | 53.0342 | 61.4222 | 74.2519 |
| 4 hours | 30.2291 | 44.8420 | 54.3720 | 63.6487 | 76.0226 |
Observation 3.6: the distribution widens with the bar size. The 95th percentile rises from 70.4023 on five-minute bars to 76.0226 on four-hour bars. The threshold 70 sits almost exactly at the 95th percentile on five-minute bars and well inside it on four-hour bars. The same number points at a different place in the distribution.
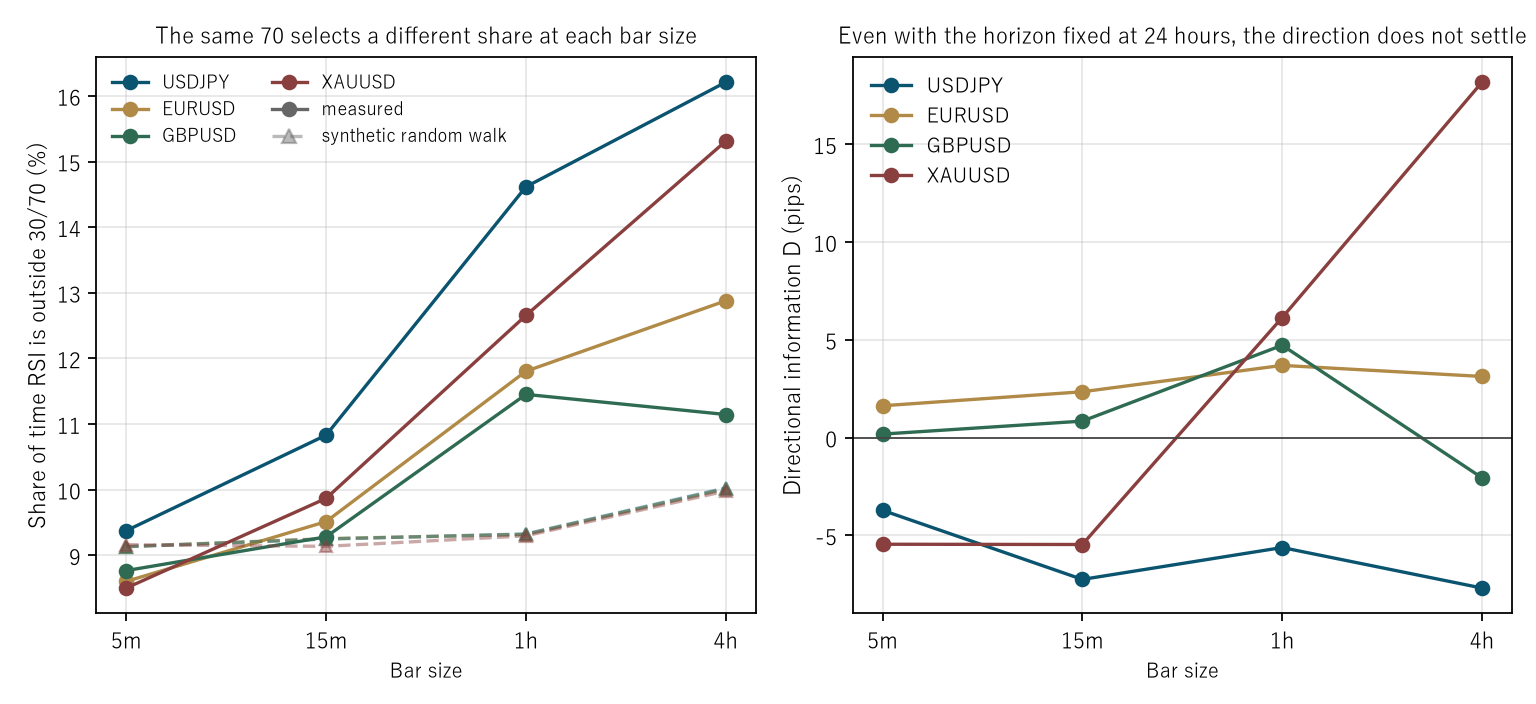
Figure 1: on the left the share of time outside the thresholds (circles measured, dashed triangles the synthetic random walk); on the right the directional information. The random-walk lines are nearly flat and only the measurement rises.
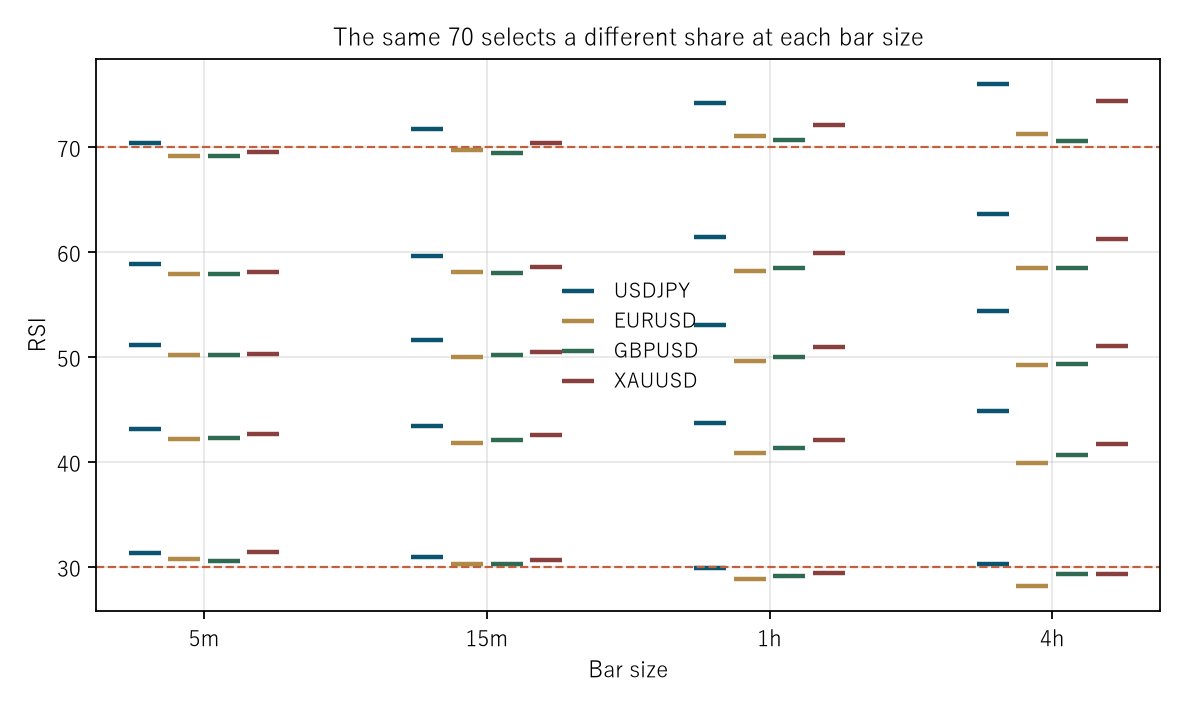
Figure 2: the five quantiles of RSI at each bar size, for the four series. The dashed lines mark 30 and 70. As the bar grows, the distribution widens and the thresholds move inward relative to it.
4. Moving the thresholds and the period
Calculation 4.1 Moving the thresholds (bar size fixed at one hour, evaluation period)
| Instrument | 40/60 share | 40/60 D | 30/70 share | 30/70 D | 20/80 share | 20/80 D |
|---|---|---|---|---|---|---|
| USDJPY | 46.3476% | −3.5395 | 14.6152% | −5.6184 | 2.4349% | −3.7672 |
| EURUSD | 43.7147% | 1.9198 | 11.8048% | 3.6954 | 1.5594% | 3.1672 |
| GBPUSD | 43.2696% | 2.0151 | 11.4524% | 4.7249 | 1.1805% | −5.9047 |
| XAUUSD | 45.0014% | −1.5155 | 12.6550% | 6.1395 | 1.5090% | 27.3643 |
Observation 4.2: moving the thresholds from 60 to 80 changes the share selected by a factor of 19.0345 (USDJPY) to 36.6540 (GBPUSD). Choosing a threshold is choosing how rare an event to pick up.
Observation 4.3: the 27.3643 pips at 20/80 for XAUUSD looks large, but the share behind it is only 1.5090%. Values where the share is small come from few observations.
Calculation 4.4 Moving the period (one-hour bars, thresholds 30/70, evaluation period)
| Instrument | n=7 share | n=7 D | n=14 share | n=14 D | n=21 share | n=21 D |
|---|---|---|---|---|---|---|
| USDJPY | 28.3179% | −5.6936 | 14.6152% | −5.6184 | 8.3347% | −2.4805 |
| EURUSD | 26.5217% | 3.8828 | 11.8048% | 3.6954 | 5.9192% | 5.3601 |
| GBPUSD | 26.1217% | 2.0488 | 11.4524% | 4.7249 | 5.2423% | 3.5941 |
| XAUUSD | 26.8420% | −1.7255 | 12.6550% | 6.1395 | 6.4876% | 6.8582 |
Observation 4.5: a shorter period makes RSI move more easily and increases the share outside. Bar size, threshold and period all move the share. All three are quantities set by the person choosing.
5. Measuring the directional information
Calculation 5.1 Directional information by bar size (evaluation period, horizon twenty-four hours)
| Instrument | Bar size | Count | D (overall) | Dd (daily) | Daily t | Per day | spr |
|---|---|---|---|---|---|---|---|
| USDJPY | 5 min | 20,035 | −3.7140 | 1.7842 | 0.88 | 20.5 | 0.60 |
| USDJPY | 15 min | 7,717 | −7.2479 | 5.6572 | 1.99 | 8.0 | 0.60 |
| USDJPY | 1 hour | 2,602 | −5.6184 | 9.2014 | 2.32 | 4.0 | 0.60 |
| USDJPY | 4 hours | 780 | −7.6892 | 1.9489 | 0.36 | 3.0 | 0.60 |
| EURUSD | 5 min | 18,443 | 1.6300 | 1.6324 | 1.55 | 19.0 | 0.30 |
| EURUSD | 15 min | 6,794 | 2.3461 | 7.5878 | 5.34 | 7.0 | 0.30 |
| EURUSD | 1 hour | 2,107 | 3.6954 | 11.7607 | 5.46 | 3.0 | 0.30 |
| EURUSD | 4 hours | 621 | 3.1291 | 8.2494 | 2.85 | 2.0 | 0.30 |
| GBPUSD | 5 min | 18,791 | 0.1821 | 2.3702 | 1.55 | 20.0 | 0.90 |
| GBPUSD | 15 min | 6,635 | 0.8455 | 10.8318 | 5.44 | 7.0 | 0.90 |
| GBPUSD | 1 hour | 2,047 | 4.7249 | 16.9740 | 5.29 | 3.0 | 0.90 |
| GBPUSD | 4 hours | 537 | −2.0528 | 10.1360 | 2.42 | 2.0 | 0.90 |
| XAUUSD | 5 min | 17,815 | −5.4496 | 2.7598 | 0.66 | 19.0 | 3.50 |
| XAUUSD | 15 min | 6,894 | −5.4632 | 20.5919 | 3.89 | 7.0 | 3.50 |
| XAUUSD | 1 hour | 2,214 | 6.1395 | 39.6301 | 5.12 | 3.0 | 3.54 |
| XAUUSD | 4 hours | 725 | 18.1759 | 41.0519 | 3.75 | 2.0 | 3.57 |
Observation 5.2: the daily-clustered t reaches 2 in absolute value in 10 of the 16 cells. By chance about 0.7 would be expected, so stopping here reads as "the mean-reverting use of RSI works".
Observation 5.3: and the daily means are large: 41.0519 pips for XAUUSD on four-hour bars, 16.9740 pips for GBPUSD on one-hour bars. They greatly exceed the spread (0.30 to 3.57).
Observation 5.4: yet the overall mean and the daily mean disagree in sign in 7 of the 16 cells. USDJPY on one-hour bars is −5.6184 overall and 9.2014 daily. Something already fails to line up here.
Observation 5.5: and the shape that should prompt suspicion of overlap is present. On five-minute bars there are 20.5 entries a day and the horizon is twenty-four hours. Adjacent observations share 287 of their 288 minutes.
6. The baseline — a random walk should not depend on bar size
As written in Section 1, on a series of independent increments the distribution of RSI should not depend on bar size. Whether it does is measured.
Calculation 6.1 The share on synthetic random walks (median of 20 realisations, evaluation period)
| Instrument | 5 min | 15 min | 1 hour | 4 hours | Max ÷ min |
|---|---|---|---|---|---|
| USDJPY | 9.1317% | 9.2489% | 9.3255% | 10.0270% | 1.0980 |
| EURUSD | 9.1335% | 9.2568% | 9.3147% | 10.0062% | 1.0955 |
| GBPUSD | 9.1316% | 9.2492% | 9.3208% | 10.0145% | 1.0967 |
| XAUUSD | 9.1616% | 9.1371% | 9.2969% | 9.9789% | 1.0921 |
Observation 6.2: on random walks the ratio is between 1.0921 and 1.0980, essentially flat. Prediction B holds there.
Observation 6.3: the measured ratio had a median of 1.6130. The dependence of the share on bar size therefore does not come from the definition of RSI; it comes from the market.
Observation 6.4: it is tempting to read this as "so there is structure in the market". That reading is correct, and it says nothing about direction. The share depending on bar size and the direction being right are different things.
7. Removing the overlap — and the baseline on the directional side
Calculation 7.1 Measuring again with non-overlapping windows (evaluation period)
Keeping one observation every h bars so that the windows examined do not overlap.
| Instrument | Bar size | Count with overlap | D | Daily t | Count without | D | t |
|---|---|---|---|---|---|---|---|
| USDJPY | 5 min | 20,035 | −3.7140 | 0.88 | 47 | −13.8170 | −0.79 |
| USDJPY | 15 min | 7,717 | −7.2479 | 1.99 | 97 | −15.0825 | −1.59 |
| USDJPY | 1 hour | 2,602 | −5.6184 | 2.32 | 86 | −17.2500 | −1.46 |
| USDJPY | 4 hours | 780 | −7.6892 | 0.36 | 129 | −10.3709 | −1.14 |
| EURUSD | 5 min | 18,443 | 1.6300 | 1.55 | 83 | 4.9078 | 0.83 |
| EURUSD | 15 min | 6,794 | 2.3461 | 5.34 | 107 | 13.3626 | 2.30 |
| EURUSD | 1 hour | 2,107 | 3.6954 | 5.46 | 82 | 5.0415 | 0.82 |
| EURUSD | 4 hours | 621 | 3.1291 | 2.85 | 94 | 2.1005 | 0.46 |
| GBPUSD | 5 min | 18,791 | 0.1821 | 1.55 | 64 | −0.2133 | −0.03 |
| GBPUSD | 15 min | 6,635 | 0.8455 | 5.44 | 65 | −20.3808 | −2.27 |
| GBPUSD | 1 hour | 2,047 | 4.7249 | 5.29 | 89 | 6.3421 | 0.77 |
| GBPUSD | 4 hours | 537 | −2.0528 | 2.42 | 81 | −6.9747 | −0.81 |
| XAUUSD | 5 min | 17,815 | −5.4496 | 0.66 | 68 | −5.2005 | −0.23 |
| XAUUSD | 15 min | 6,894 | −5.4632 | 3.89 | 74 | 4.5736 | 0.21 |
| XAUUSD | 1 hour | 2,214 | 6.1395 | 5.12 | 93 | −3.0142 | −0.18 |
| XAUUSD | 4 hours | 725 | 18.1759 | 3.75 | 120 | 14.6439 | 0.89 |
Observation 7.2: the cells whose daily t reaches 2 in absolute value fall from 10 of 16 to 2 of 16. The count falls to a median of 0.0244 of itself.
Observation 7.3: the sign reverses in 4 of the 16 cells. GBPUSD on fifteen-minute bars goes from 0.8455 to −20.3808, and its t still exceeds 2 in absolute value with the opposite sign.
Observation 7.4: clustering by day folds only the overlap within a day. With a twenty-four-hour horizon, the overlap across days remains. The t values of Section 5 were failing to count it.
Observation 7.5: removing the overlap, however, leaves between 47 and 129 observations. The power of the test falls sharply. "Down to 2" is not "there is none"; it is not visible at this count.
Calculation 7.6 The baseline on the directional side (one-hour bars, evaluation period)
| Instrument | Measured D | Measured Dd | Median random D | Random minimum | Random maximum | Inside? |
|---|---|---|---|---|---|---|
| USDJPY | −5.6184 | 9.2014 | −0.7568 | −10.2575 | 13.9151 | yes |
| EURUSD | 3.6954 | 11.7607 | −0.4668 | −6.7974 | 9.5068 | yes |
| GBPUSD | 4.7249 | 16.9740 | −0.7607 | −9.9501 | 13.7297 | yes |
| XAUUSD | 6.1395 | 39.6301 | 1.5722 | −21.7173 | 31.4311 | yes |
Observation 7.7: in all four series the measured value falls inside the range of the 20 realisations. On the share side the measurement and the random walk separated clearly (Section 6); on the directional side they do not.
Observation 7.8: placing those two side by side gives the answer of this paper. Changing the bar size moves the share selected (it separates from the random walk) but does not move the direction (it does not).
8. Splitting by session
Design: five non-overlapping bins in Coordinated Universal Time — Tokyo 0–7, London 7–12, overlap 12–16, late New York 16–21, and night 21–24. Bars are one hour.
Calculation 8.1 Directional information in each of the five bins (evaluation period)
| Instrument | Tokyo 0–7 | London 7–12 | Overlap 12–16 | NY late 16–21 | Night 21–24 |
|---|---|---|---|---|---|
| USDJPY | −9.78 (t −0.01) | −3.97 (t 0.46) | −0.10 (t 0.55) | −3.43 (t −0.14) | −15.41 (t −1.58) |
| EURUSD | 10.51 (t 2.40) | 4.65 (t 2.11) | −0.50 (t 1.53) | 1.11 (t 0.98) | 2.77 (t −0.01) |
| GBPUSD | 11.15 (t 1.46) | 0.65 (t 0.99) | 3.25 (t 2.80) | 5.83 (t 1.69) | −0.27 (t 0.59) |
| XAUUSD | 13.92 (t 2.37) | 25.57 (t 1.16) | −3.16 (t 1.35) | −9.61 (t 0.83) | 18.50 (t 1.50) |
Observation 8.2: the daily t reaches 2 in absolute value in 4 of the 20 cells. By chance about 0.9 would be expected, so the measured figure exceeds it.
Observation 8.3: but this table does not remove the overlap. In Section 7, removing it dropped the same kind of t from 10 to 2. The t values split by session must be discounted by the same amount.
Observation 8.4: trying five bins, finding one that looks significant is the ordinary case. What is read is whether the number of significant cells exceeds chance. And comparing a figure that has not been corrected for overlap against chance means little.
9. Limitations
- Removing the overlap cuts the count by two orders of magnitude. At 47 to 129 observations, even an effect several times the spread would not be visible. "Not significant" is not "not there".
- Only one way of removing the overlap is used. The grid taking one observation every h bars is placed one way; versions with a shifted start are not measured.
- The measurement uses a fixed horizon. It does not use an exit that cuts at a take-profit or a stop-loss.
- Only the mean-reverting reading is measured. The trend-following reading is read off by flipping the sign, but divergence — a disagreement between price and RSI — is not a question about thresholds and is not treated.
- The synthetic baseline uses independent normal increments. Volatility clustering is not included. Part of the separation on the share side may come from there, but that has not been measured.
- The session table is not corrected for overlap (Observation 8.3).
- Four instruments over six years. Nothing is said about other markets or other periods.
Conclusion
The 70 of RSI looks as though it points at a state of the market. But the share the same 70 selects runs from 8.5015% on five-minute bars to 16.2095% on four-hour bars. Since that ratio is a flat 1.09 on a series of independent increments, what moves is the market side.
That much is a fact about the market. It says nothing about direction. On the directional side, removing overlapping windows dropped the cells with a daily t above 2 from 10 to 2, and all four series fell inside the range of the random walk.
One thing separates the cases — when the bar size moved, was it the share selected that moved or the direction? Only the share moved.
And the heaviest lesson of this paper is the gap between Sections 5 and 7. Measuring twenty-four hours ahead while entering every five minutes counts the same event many times over. Averaging within days is not enough. Write the horizon and the interval between entries side by side.
Data and reproduction
| Data | Currency ticks from Dukascopy (agreement to the millisecond, bid and ask, verified from 2019 onward). Gold from Dukascopy |
| Period | 2019–2024 (six years). Selection 2019–2021 / evaluation 2022–2024 |
| Instruments | USDJPY, EURUSD, GBPUSD, XAUUSD |
| Bars | 5 min, 15 min, 1 hour, 4 hours. Mid price, closing value of completed bars only. Bars with no ticks are not created |
| Verification | 検算/F004.py (with --zu it also writes the figures). Every number in the text is taken from 検算/F004_output.txt |
| Figures | 図/F004_zu1, 図/F004_zu2 (png, svg, English versions) |
| Random seeds | Fixed at 0–19. Re-running gives the same values |
| Audit of the foundation | _ツール/audit_bars.py (look-ahead in the bars, daylight saving, the day boundary). The record is _土台の検査.txt |
References
- Yamagishi, Y. (2026). Inside One Phenomenon Live a Number That Moves with the Lattice and a Number That Does Not [Paper 264]. Zenodo. 10.5281/zenodo.22169720
- Yamagishi, Y. (2026). The Condition Named as the Core of a Rule Does Nothing [Paper 422]. Zenodo. 10.5281/zenodo.22700081
- Yamagishi, Y. (2026). The Multiplier of a Bollinger Band Changes How Often Price Leaves It, Not Which Way Price Goes [F003]. Zenodo. 10.5281/zenodo.22881085
Reference
Yamagishi, Y. (2026). The "Overbought 70" of RSI Belongs to the Bar Size You Chose [F004]. Zenodo.
DOI: 10.5281/zenodo.22881156
YOI: https://www.yamagishiyuuki.com/yoi/F004
ORCID: 0009-0006-8587-3450
PDF (English) · PDF (Japanese) · Date proof of the English PDF (OpenTimestamps .ots) · SHA256SUMS
The record page for this paper (in Japanese, with the PDFs in each language and the date proof): YOI F004. This paper is a preprint and has not been peer reviewed.