Abstract
What this paper asks is what a report of "the sign changed when the top few days were dropped" actually says — and the answer is: very nearly just the arithmetic of the dropping. No new mathematical theorem and no new law is claimed.
First, dropping the top lowers the mean of any series whatsoever. Among cells whose mean of daily means is positive, dropping the top 5 days leaves 0.3076 of them at or below zero, and dropping the top 10% of days leaves 0.8994 (Section 4).
Second, and this is the core. ★ Hold the number of dropped days fixed and choose them at random, and almost nothing happens. It is 0.0000 for a random 5 days and 0.0036 for a random 10%. The value itself barely moves either: 1.2847 becomes 1.2900 (Section 4).
Third, even on a synthetic random walk, where the directional information is zero by construction, dropping the top 5 days leaves 0.1376 of the cells at or below zero. This test works just as well on a series that is right about nothing (Section 6).
Fourth, the contribution share is close to a restatement of "spread ÷ mean". The correlations are 0.9990, 0.9905, 0.9995 and 0.9983. Since the number of days is nearly constant, this is not a discovery but very nearly an identity (Section 5).
Fifth, of the predictions written before measuring, "the fewer the days the larger the share" failed. The correlation between share and number of days is +0.0649 to +0.1175, and the half with more days has the higher share (Section 5).
Sixth, the measured share (median 0.6394) is larger than the synthetic random walk's (0.2853). ★ But that is not because the tail is heavier. The median spread is 55.0426 on the measurement against 59.6483 on the random walk — larger on the random walk — and what differs is the level of the mean (1.7303 against 3.0074) (Section 6).
Scope of this paper: No new mathematical theorem and no new law is claimed — order statistics, selection bias and random walks are all known. No real course or its proponent is discussed — no real teaching material, author, or vendor is the subject here, and none is named. What this paper inspects is a test the author himself has been using. Trading is not discussed — what is measured is directional information, not trading performance including commissions, fills and money management. The scope is intraday and few instruments — four instruments, six years, one-hour bars. Monthly time-series momentum (dozens of markets, one to twelve month holds) is documented in the academic literature and is not contradicted here. One sweep is fixed — four families (Section 7). Only positive cells are looked at — so the difference in mean between the measurement and the random walk may be a product of that choice, which is not separated here (Sections 6 and 7). The overlap is not removed — horizons of 6, 24 and 72 bars overlap, and no t value is reported (Section 7). This paper does not say to discard the test — what it says is that it cannot be read without the control and the baseline beside it (Conclusion). No forecast is claimed. Relation to earlier papers: F021 showed that the ranking of a sweep does not carry across periods and F022 that the best value is a function of how many cells were looked at — this paper inspects the test used to kill candidates in the same way. What is added is placing a control that drops the same number of days at random, measuring what the contribution share is a restatement of, and running the same test on a series with zero directional information.
1. Notation and the question
When killing a candidate, one writes things like: "dropping the top 5 days flipped the sign, so this candidate rides on a handful of days."
| What gets reported | What does not |
|---|---|
| The value after dropping the top few days | What happens when the same number is dropped at random |
| That the sign changed | How many days there were in all |
| The share of the total made by the top | What the same test does on a series with no edge |
Observation 1.1: Dropping the top lowers the mean of any series whatsoever. Remove the largest observations and the rest must average lower, so this is arithmetic, not the fragility of that candidate.
Observation 1.2: ★ A comparison partner is therefore needed. The natural one is the same number of days, chosen at random. Random dropping is unbiased, so the mean should neither rise nor fall.
Observation 1.3: The separator is which days were dropped. The number of days, the data, the period and the instruments are all held fixed, and only the choosing is varied.
Observation 1.4: ★ And one more thing is needed: how many cells fall when the same test is run on a series with zero directional information by construction.
Question: what does "the sign changed when the top few days were dropped" actually say?
2. State the quantity and the design first
Predictions (written before running)
① Dropping the top lowers the mean of any series. This is arithmetic, not fragility.
② Dropping the same number of days at random neither raises nor lowers the mean (unbiased).
③ A synthetic random walk with zero directional information falls by the same amount.
④ The contribution share grows as the number of days shrinks.
Design (declared before running and not changed during it)
| Item | Decision |
|---|---|
| Grid | One-hour bars, mid prices, completed bars only |
| Moving-average cross | Fast 3, 5, 8, 12, 20, 30 × slow 20, 30, 50, 80, 120, 200 (fast < slow) |
| RSI | Period 7, 14, 21 × threshold 20, 30, 40 |
| Outside a band | Period 10, 20, 40 × multiplier 1.5, 2.0, 2.5, 3.0 |
| High-low breakout | Period 10, 20, 50, 100 |
| Horizon | 6, 24, 72 bars |
| Subject | Only cells whose mean of daily means is positive (what could be called a candidate) |
| Dropping | Top 5 days / random 5 days / top 10% of days / random 10% of days |
| Random draws | Mean of 200 draws |
| Baseline | Synthetic random walk down to within-bar movement (5 series) |
| Instruments | USDJPY, EURUSD, GBPUSD, XAUUSD |
| Period | 2019–2024 (six years taken as one, to get many days) |
Observation 2.1: ★ The number of days dropped is the same whether from the top or at random. All that differs is how they were chosen.
Observation 2.2: Days are averaged first and then lined up. This keeps days with many observations from making the whole average, and it is the construction this series uses throughout.
Observation 2.3: Only positive cells are looked at, since a cell that was already negative cannot have its sign change. That this restriction is itself a selection is handled in Sections 6 and 7.
The bar counts are 36,534, 36,554, 36,535 and 34,892.
3. How much of the total do the top few days make?
Calculation 3.1 Contribution share (cells whose mean of daily means is positive)
| Instrument | Cells | Median days | Top-5-day share | Top-10%-day share | Spread ÷ mean |
|---|---|---|---|---|---|
| USDJPY | 137 | 1864 | 0.7591 | 7.8047 | 40.5226 |
| EURUSD | 124 | 1868 | 0.3282 | 4.9793 | 25.1954 |
| GBPUSD | 154 | 1864 | 0.7616 | 8.2757 | 43.2779 |
| XAUUSD | 132 | 1822 | 0.5197 | 6.9777 | 36.9448 |
Observation 3.2: The top-5-day share has a median of 0.6394. The median number of days is 1,864, so 5 days is only 0.2682% of the whole. That 0.2682% makes six tenths of the total.
Observation 3.3: The top-10%-day share has a median of 7.3912, far above 1. ★ The ratio exceeds 1 because the total itself is small. Adding the remaining days gives a negative number, so the sum of the top alone is larger than the total.
Observation 3.4: ★ The contribution share is therefore a quantity that diverges as the total approaches zero. "The top few made ninety per cent of the profit" looks like a statement about the weight of the tail while sometimes being a statement about the smallness of the total.
Observation 3.5: Spread ÷ mean runs from 25.1954 to 43.2779. The mean per day is on the order of 1 pip while the day-to-day spread is tens of pips. That this ratio is large is itself why the top few days stand out.
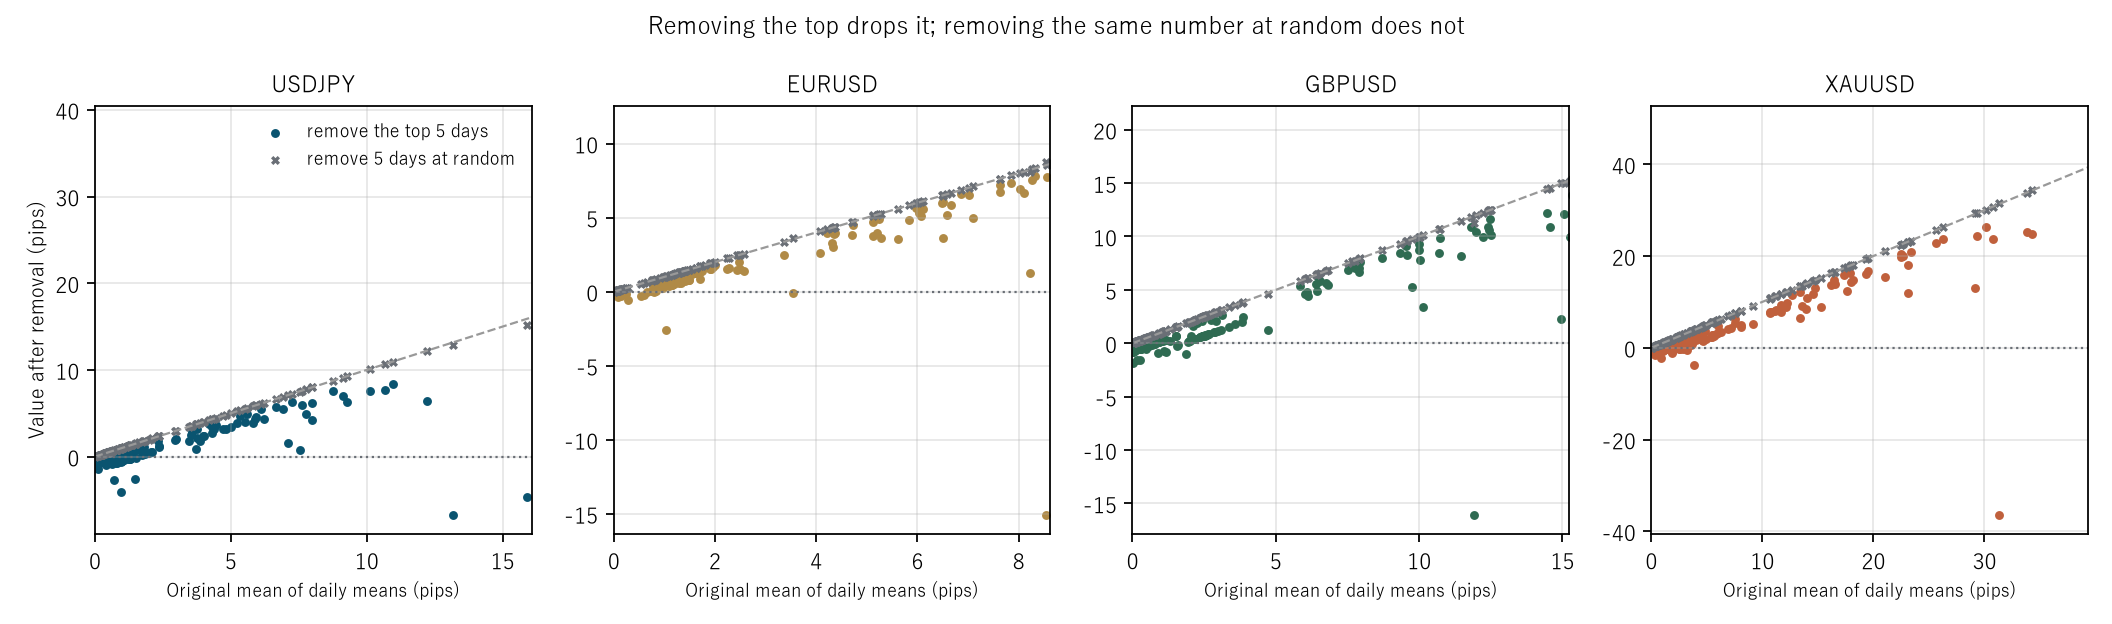
Figure 1: horizontal is the original mean of daily means, vertical is the value after dropping. Circles drop the top 5 days; crosses drop 5 days at random.
4. Place dropping the top beside dropping the same number at random
Calculation 4.1 Value after dropping (mean of daily means, pips)
| Instrument | Original | Top 5 dropped | Random 5 dropped | Top 10% dropped | Random 10% dropped |
|---|---|---|---|---|---|
| USDJPY | 1.2847 | 0.4020 | 1.2900 | −9.6098 | 1.3500 |
| EURUSD | 1.4635 | 0.9849 | 1.4656 | −5.5055 | 1.4922 |
| GBPUSD | 1.9971 | 0.3595 | 1.9987 | −9.5015 | 1.9912 |
| XAUUSD | 4.7896 | 2.1833 | 4.7755 | −25.2823 | 4.6726 |
Calculation 4.2 Share of cells left at or below zero
| Instrument | Top 5 dropped | Random 5 dropped | Top 10% dropped | Random 10% dropped |
|---|---|---|---|---|
| USDJPY | 0.3577 | 0.0073 | 0.9489 | 0.0073 |
| EURUSD | 0.2177 | 0.0000 | 0.8548 | 0.0000 |
| GBPUSD | 0.4026 | 0.0000 | 0.8896 | 0.0130 |
| XAUUSD | 0.2576 | 0.0000 | 0.9091 | 0.0000 |
Observation 4.3: ★ This is the core. Dropping the top 5 days leaves 0.3076 of the cells at or below zero, and dropping 5 days at random leaves 0.0000. For the top 10% it is 0.8994 against 0.0036 for a random 10%.
Observation 4.4: The value itself does not move either. USDJPY goes from 1.2847 to 1.2900 with a random 5 dropped and to 1.3500 with a random 10% dropped. The dropping is unbiased, exactly as predicted.
Observation 4.5: Dropping the top 10% of days gives large negatives, from −5.5055 to −25.2823 pips. Given that the originals were +1.4635 to +4.7896, this is not "fragile" — it is that the day-to-day spread is tens of times the mean to begin with.
Observation 4.6: ★ So "the sign changed when the top N days were dropped" says nothing on its own. Only with the version that drops the same number at random beside it does it become a contrast.
Observation 4.7: This paper does not say to discard the test. Dropping the top is meant to see whether a result rides on a handful of days, and for that purpose it is fit. What it says is that reporting it requires the control and the number of days beside it.
5. What is the contribution share determined by?
Calculation 5.1 Correlations with the share
| Instrument | Share vs number of days | Share vs "spread ÷ mean" | Days vs "spread ÷ mean" |
|---|---|---|---|
| USDJPY | 0.0649 | 0.9990 | 0.0806 |
| EURUSD | 0.1175 | 0.9905 | 0.1960 |
| GBPUSD | 0.0793 | 0.9995 | 0.0858 |
| XAUUSD | 0.1015 | 0.9983 | 0.1163 |
Calculation 5.2 Share split by number of days (top 5 days)
| Instrument | Fewer-days half | More-days half | Difference |
|---|---|---|---|
| USDJPY | 0.3651 | 1.0385 | −0.6734 |
| EURUSD | 0.2162 | 0.6176 | −0.4014 |
| GBPUSD | 0.2622 | 1.2017 | −0.9395 |
| XAUUSD | 0.2775 | 0.7775 | −0.4999 |
Observation 5.3: ★ Prediction ④ failed. It said "the fewer the days the larger the share", but the correlation is a weak positive +0.0649 to +0.1175, and the half with more days has the higher share (differences −0.4014 to −0.9395).
Observation 5.4: Instead, the share correlates with "spread ÷ mean" at 0.9905 to 0.9995. ★ But this is not a discovery. The share is "sum of the top 5 days ÷ days × mean", and since the number of days is nearly constant (1822 to 1868), it is very nearly a linear function of spread ÷ mean.
Observation 5.5: A correlation of 0.99 is therefore very nearly an identity. It is not an agreement between two separate quantities. When values agree, whether they are the same quantity must be checked first.
Observation 5.6: ★ Read another way, the share measures not "is it concentrated" but "how many times the mean is the day-to-day spread". In market daily returns that ratio is tens of times to begin with, so a large share is the default.
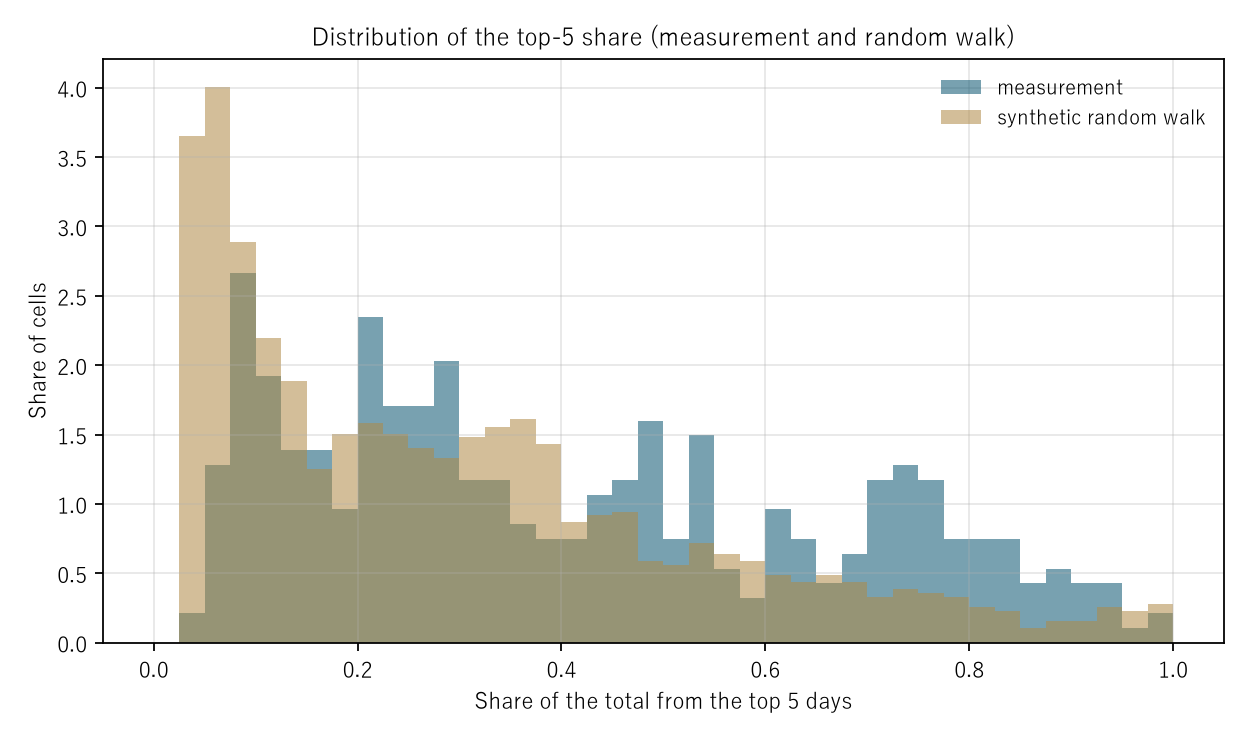
Figure 2: horizontal is the top-5-day share, vertical is the share of cells. The darker histogram is the measurement, the lighter one the synthetic random walk.
6. Baseline — do the same thing on a series with zero directional information
Calculation 6.1 The same test on a synthetic random walk (5 series)
| Instrument | Original | Top 5 dropped | Random 5 dropped | Top-5 share | Share at or below zero | |
|---|---|---|---|---|---|---|
| USDJPY | measured | 1.2847 | 0.4020 | 1.2900 | 0.7591 | 0.3577 |
| USDJPY | random | 3.0702 | 2.0265 | 3.0533 | 0.2739 | 0.1135 |
| EURUSD | measured | 1.4635 | 0.9849 | 1.4656 | 0.3282 | 0.2177 |
| EURUSD | random | 1.9445 | 1.2248 | 1.9433 | 0.3351 | 0.1429 |
| GBPUSD | measured | 1.9971 | 0.3595 | 1.9987 | 0.7616 | 0.4026 |
| GBPUSD | random | 2.9447 | 1.9099 | 2.9099 | 0.2966 | 0.1333 |
| XAUUSD | measured | 4.7896 | 2.1833 | 4.7755 | 0.5197 | 0.2576 |
| XAUUSD | random | 9.3234 | 6.6309 | 9.4041 | 0.2607 | 0.1419 |
Calculation 6.2 Is the difference a heavier tail or a smaller mean?
| Instrument | Mean | Spread | Spread ÷ mean | |
|---|---|---|---|---|
| USDJPY | measured | 1.2847 | 56.6532 | 40.5226 |
| USDJPY | random | 3.0702 | 60.2208 | 21.3132 |
| EURUSD | measured | 1.4635 | 35.7303 | 25.1954 |
| EURUSD | random | 1.9445 | 39.9935 | 26.0347 |
| GBPUSD | measured | 1.9971 | 53.4320 | 43.2779 |
| GBPUSD | random | 2.9447 | 59.0759 | 23.6314 |
| XAUUSD | measured | 4.7896 | 142.6234 | 36.9448 |
| XAUUSD | random | 9.3234 | 143.5704 | 17.1027 |
Observation 6.3: ★ Even on a series with zero directional information, dropping the top 5 days leaves 0.1376 of the cells at or below zero, and the median share is 0.2853. This test works just as well on a series that is right about nothing.
Observation 6.4: The measurement does fall further. The difference in share is a median of +0.3620 (range −0.0069 to +0.4851), and the difference in the share left at or below zero is a median of +0.1799 (range +0.0749 to +0.2693).
Observation 6.5: ★ But that difference is not a heavier tail. The median spread is 55.0426 on the measurement against 59.6483 on the random walk — larger on the random walk. What differs is the level of the mean, 1.7303 against 3.0074.
Observation 6.6: ★ With comparable spread and a smaller mean, the share grows automatically, since the share is very nearly a linear function of spread ÷ mean (Section 5). That the measurement looks concentrated is a restatement of its small gain per day.
Observation 6.7: ★ And that difference in mean may itself be a product of the choosing. This paper looks only at cells whose mean of daily means is positive. The synthetic series has more cell-to-cell spread, so taking only the positive ones from it gives a higher level. This confound is not separated here.
7. Limitations
- ★ Prediction ④ failed. "The fewer the days the larger the share" does not hold; the half with more days was higher. This paper writes that failure and does not hide it.
- ★ Only positive cells are looked at. So the difference in mean between the measurement and the random walk may be a product of that choice. This confound is not separated here.
- The correlation of 0.99 between the share and "spread ÷ mean" is very nearly an identity. With the number of days nearly constant the relation is linear. It is not an agreement between two independent quantities.
- One sweep is fixed. Four families. Other families or granularities give other figures.
- The overlap is not removed. Horizons are 6, 24 and 72 bars and the observations overlap. No t value is reported and significance is not discussed.
- Only four ways of dropping are used: top 5 days, random 5 days, top 10% of days, random 10% of days.
- The synthetic series uses independent normal increments. Volatility clustering is not included. With clustering the random walk's share should rise, which moves the gap against the measurement further toward zero. That was not measured.
- Four instruments over six years. Nothing is said about other markets or other periods.
Conclusion
Dropping the top 5 days leaves 0.3076 of the cells at or below zero, and the top 10% leaves 0.8994. The sign does indeed change often.
But dropping the same number of days chosen at random leaves 0.0000 and 0.0036. The value itself only goes from 1.2847 to 1.2900.
What fell is the arithmetic of the dropping.
And even on a synthetic random walk with zero directional information, dropping the top 5 days leaves 0.1376 of the cells at or below zero with a median share of 0.2853. This test works on a series that is right about nothing.
The measurement does fall further (a median of +0.1799 in the share left at or below zero). ★ But that is not a heavier tail. The median spread is 55.0426 on the measurement and 59.6483 on the random walk — larger on the random walk — and what differs is the level of the mean (1.7303 against 3.0074). And that difference in mean may itself be a product of looking only at positive cells.
★ The contribution share measures not "is it concentrated" but "how many times the mean is the day-to-day spread". In markets that ratio already runs from 25.1954 to 43.2779, so the top few days standing out is the default.
This paper does not say to discard the test. Dropping the top is meant to see whether a result rides on a handful of days, and for that purpose it is fit. What it says is that a report of it needs the control that drops the same number at random, and the number of days there were in all, beside it.
Data and reproduction
| Data | FX is Dukascopy-derived tick data (from 2019 onward, confirmed identical down to the millisecond, bid and ask). Gold is Dukascopy |
| Period | 2019–2024 (six years taken as one) |
| Instruments | USDJPY, EURUSD, GBPUSD, XAUUSD |
| Bars | One-hour bars, mid prices, closes of completed bars only. No bar is made where there are no ticks |
| Sweep | Moving-average cross, RSI, outside a band, high-low breakout × horizons of 6, 24 and 72 bars |
| Subject | Only cells whose mean of daily means is positive |
| Dropping | Top 5 days / random 5 days / top 10% of days / random 10% of days. Random is the mean of 200 draws |
| Verification | 検算/F023.py (--zu also writes the figures). Every figure in the text comes from 検算/F023_output.txt |
| Figures | 図/F023_zu1, 図/F023_zu2 (png, svg, English versions) |
| Random seeds | Fixed. Re-running gives the same values |
| Foundation check | _ツール/audit_bars.py (bar look-ahead, daylight saving, day boundaries). The record is _土台の検査.txt |
References
- Yamagishi, Y. (2026). The Ranking of a Sweep Does Not Carry Across Periods [F021]. Zenodo. 10.5281/zenodo.22892047
- Yamagishi, Y. (2026). The Best Value Is a Function of How Many Cells You Looked At [F022]. Zenodo. 10.5281/zenodo.22892093
Reference
Yamagishi, Y. (2026). That the Sign Changes When You Drop the Top Few Days Is a Property of How You Dropped Them [F023]. Zenodo.
DOI: 10.5281/zenodo.22892131
YOI: https://www.yamagishiyuuki.com/yoi/F023
ORCID: 0009-0006-8587-3450
PDF (English) · PDF (Japanese) · Date proof of the English PDF (OpenTimestamps .ots) · SHA256SUMS
The record page for this paper (in Japanese, with the PDFs in each language and the date proof): YOI F023. This paper is a preprint and has not been peer reviewed.